Home, auto, Medicare, life and health policies I sort out for families by reading the fine print first, lining up carrier rates side by side, and staying available long after the paperwork is signed.
I started PryorInsuranceGuy with a simple idea: families deserve plain answers, transparent rate comparisons, and a policy that actually fits the household instead of the brochure.
Every conversation I have begins with the budget, the people under the roof, and the year ahead. From there, I compare carrier rates, translate the fine print, and help the best fitting policy rise to the top without sales pressure or surprise additions.
Tap a coverage line below to see what each plan actually does, where it tends to fit, and which fine print is worth a closer look.
The roof, the walls, and almost everything inside them stay protected against fire, theft, weather and the small disasters that show up out of nowhere on a Tuesday afternoon.
From the daily commute to a teenager getting their first license, auto coverage gets shaped around the cars in the driveway and the actual miles being driven each week.
Parts A, B, C and D rarely make sense on the first read. Sitting down with me, someone who knows the deadlines and the doctor networks, turns a confusing maze into a short checklist.
Term, whole and final-expense policies all sound similar from the outside. The right choice usually comes down to how long the coverage needs to last and what the household would need to keep running.
Premiums, deductibles, networks and out-of-pocket maximums all interact in ways the marketing pages skip over. Each plan gets compared on the numbers that actually show up on a doctor's bill.
Four small steps I walk through with every client replace the usual paperwork pile and waiting game.
A short call with me to figure out which policies actually apply and which ones can wait until later.
I place several rate quotes side by side so the price differences and coverage gaps stay obvious.
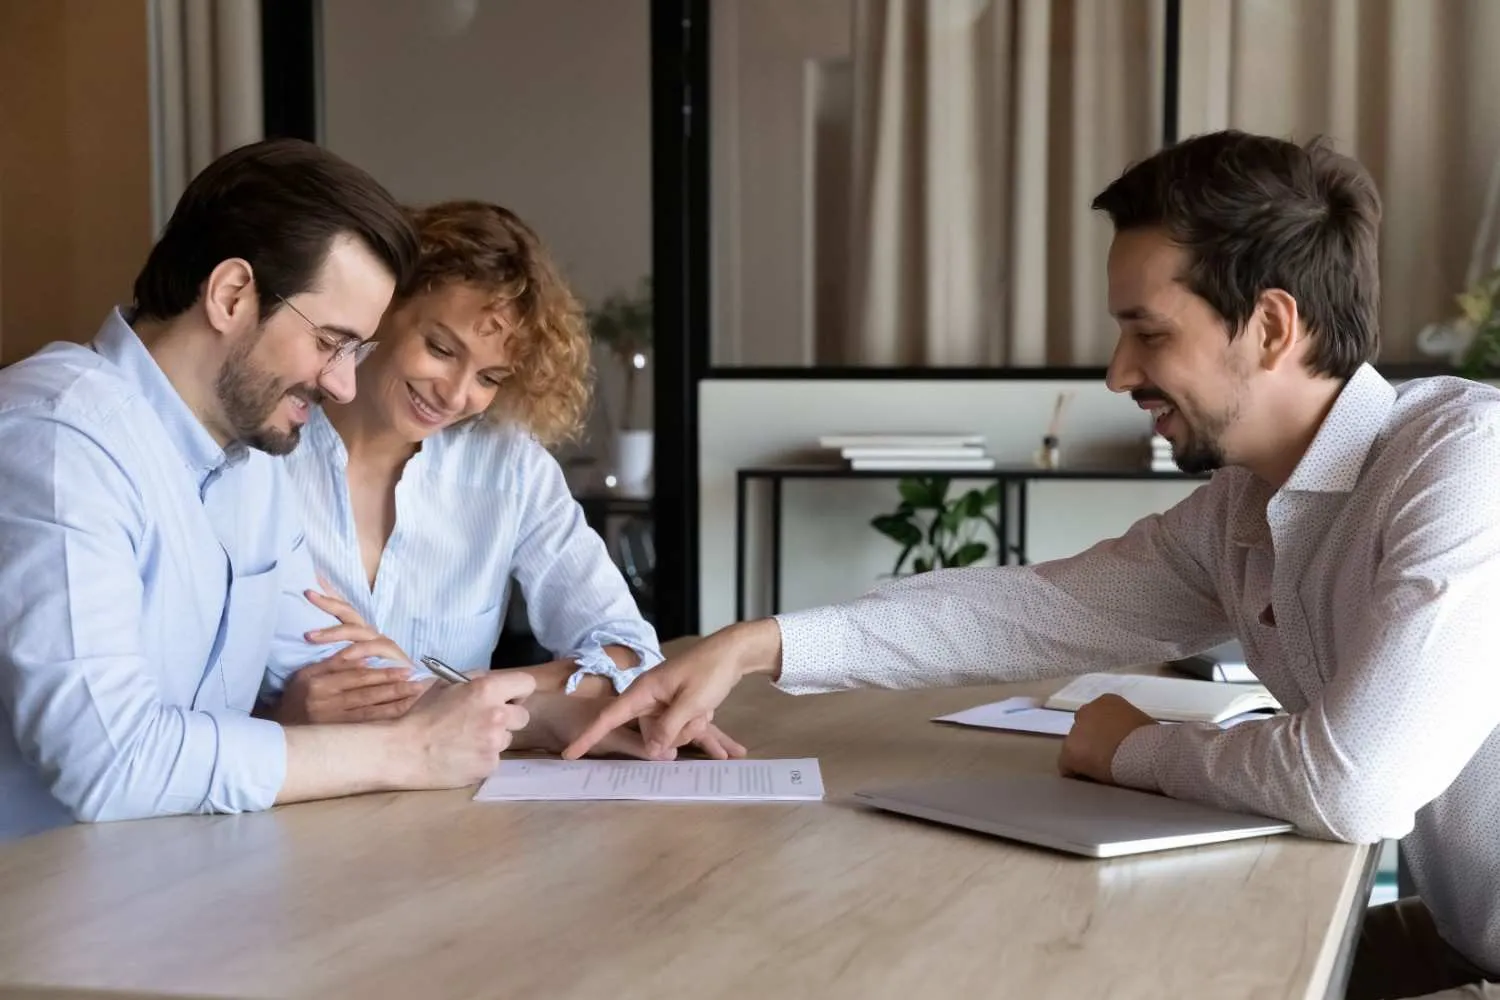
Once the right fit shows up, I walk through every line of the policy before any signature lands.
Renewals, claims questions and life changes get the same personal attention from me long after the policy starts.
Quiet conversations, careful comparisons and policies that actually fit, said better by the families who lived through the process.
The home and auto bundle saved real money the first year, but the part that stuck was getting plain answers to confusing questions instead of brochures and sales pitches.
Medicare felt impossible to figure out alone. Sitting down with a real person who knew the parts and the timing changed everything for the family this year.
Switching auto coverage usually feels like a chore, but the whole conversation took one short call and the new rate was already fairer than the old one by the end.
Life insurance used to feel like an awkward topic to even bring up. The questions were calm, the term length actually fit the mortgage, and the price made sense.
Health plans on the marketplace looked nearly identical until someone actually broke down the numbers. The deductible math finally made sense after that meeting.
A quick read for the questions that tend to come up before any paperwork is even opened.